


 PDF版 Demo
一年間無料の更新サービス
お客様はいつでもFinancial Reporting最新な勉強資料を獲得するために、我々社は常に更新の情況を確認します。だから、我々のFinancial Reporting試験勉強資料は試験問題の変化に伴って、更新しつつあります。購入日から一年間に、このような更新サービスをお客様たちに無料で提供しますので、ご安心ください。
本社のFinancial Reporting問題対策を購入すると、五分から十分までの時間にお客様のメールアドレスにお届けします。Financial Reporting勉強資料を受け取る際に、すぐにダウンロードして使用できます。使用中にFinancial Reporting試験勉強資料についてどんな疑問がある場合に、本社の係員に連絡してください。この問題に対して、弊社の社員はすぐに対応します。
我々社はFinancial Reporting勉強資料をリリースされる以来、たくさんの好評を博しました。試験に合格したお客様は「F1オンラインテストエンジンを利用して、模擬試験を繰り返して受けました。無事試験に合格しました。大変助かりました。」と感謝します。あなたの支持こそ我々は最も高品質のFinancial Reporting問題集を開発して努力します。
全額返却保証
もしお客様は本社のFinancial Reporting学習資料を使用した後、一回目にFinancial Reporting試験に通過しないなら、本社はFinancial Reporting学習資料を購入したお金を返金します。お客様は失敗したFinancial Reporting試験成績書をメールで送信します。そして、わが社の係員はその試験成績書をチェックした後で、あなたの返金要求に応じて100%返金を保証します。
F1試験問題集をすぐにダウンロード:成功に支払ってから、我々のシステムは自動的にメールであなたの購入した商品をあなたのメールアドレスにお送りいたします。(12時間以内で届かないなら、我々を連絡してください。Note:ゴミ箱の検査を忘れないでください。)
CIMA F1 試験シラバストピック:
| セクション | 比重 | 目標 |
|---|---|---|
| 税務の基本原則 | 20% | - 税務制度と税の種類 - 当期税額の計算 - 間接税の概要 - 繰延税金の概念 |
| 現金および運転資本の管理 | 25% | - 現金の管理と予測 - 運転資本の循環と管理目標 - 債権、棚卸資産、債務の管理 - 短期的な資金調達の選択肢 |
| 財務諸表 | 45% | - 単体財務諸表の作成
- 財務諸表の解釈と分析 - IFRS基準の適用
|
| 財務報告に関する規制環境 | 10% | - 概念的枠組みと規制機関 - 原則主義による規制と規則主義による規制の比較 - IFRS財団およびIASBの組織体制 - 財務報告における職業倫理 |
CIMA Financial Reporting 認定 F1 試験問題:
問題 #1
The statement of profit or loss for PQ, ST and AB for the year ended 31 December 20X0 are shown below: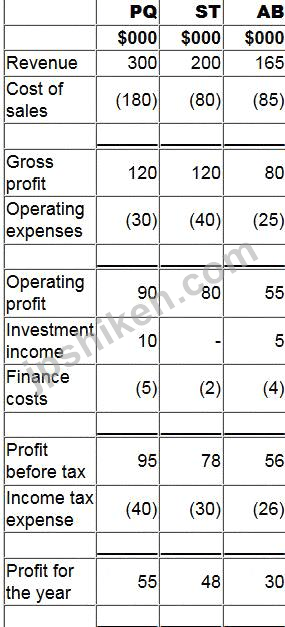
1. PQ acquired 80% of its subsidiary, ST, on 1 January 20X0 and 40% of its associate, AB, on 1 September 20X0.
2. Since acquistion PQ has sold goods to ST and AB for $20,000 and $30,000 respectively. At the year end both ST and AB have 50% of these goods remaining in inventory. PQ uses a mark-up of 20% on all of its sales.
3. Since acquisition the goodwill in respect of ST has been impaired by $8,000 and the investment in AB has been impaired by $2,000.
4. PQ uses the fair value method for non-controlling interest at acquisition.
Calculate the profit attributable to the non-controlling interests disclosed in PQ's consolidated statement of profit or loss for the year ended 31 December 20X0.
Give your answer to the nearest whole $.
問題 #2
The following information relates to AA.
Extract of Trial Balance at 31 December 20X4;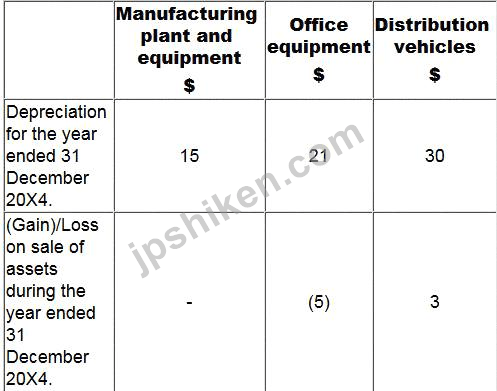
Notes
(i) Inventory at 31 December 20X4 was valued at cost at $30.
(ii) The loan which was received on 1 July 20X4 is repayable in 20X9.
(iii) Corporate income tax represents an over-provision of tax for the year ended 31 December 20X3. AA reported a loss for tax purposes for the year ended 31 December 20X4 and a tax refund is expected amounting to $20.
(iv) Cost of sales, administration and distribution costs need to be adjusted for the following:
Calculate gross profit for the year ended 31 December 20X4.
Give your answer as a whole $.
問題 #3
YZ has $40,000 of plant and machinery which was acquired on 1 June 20X1.Tax depreciation rates on plant and machinery are 25% reducing balance. All plant and machinery was sold for $24,000 on 1 June 20X3.
Calculate the tax balancing allowance or charge on disposal for the year ended 31 May 20X3 and state the effect on the taxable profit.
A. A balancing charge of $1,500 reduces taxable profit.
B. A balancing charge of $1,500 increases taxable profit.
C. A balancing allowance of $1,500 increases taxable profit.
D. A balancing allowance of $1,500 reduces taxable profit.
問題 #4
XYZ's accounting profit for the last reporting period is $200,000. This is after deduction of:
* Accounting depreciation of $40,000.
* Entertaining expenses of $10,000 which are disallowable for tax purposes
* Directors' salaries of 530.000
Tax depreciation allowances of $60,000 are available and the rate of corporate income tax is 20%.
What is the corporate tax liability of XYZ for the reporting period?
A. $44,000
B. $38,000
C. $36,000
D. $42,000
問題 #5
Country X charges corporate income tax at the rate of 20% on all income irrespective of whether it is paid out as a dividend. Country Y charges corporate income tax at the rate of 25% on all income.
An entity, AA, which is resident in Country X pays a dividend of $100,000 to another entity, BB, which is resident in Country Y.
Countries X and Y have a double taxation treaty which adopts the exemption method in respect of this type of transaction.
What is BB's liability to tax in Country Y in respect of the dividend income received?
A. Tax will be payable at 20%.
B. Tax will be payable at 25%.
C. No tax will be payable.
D. Tax will be payable at 25% less a credit given for the 20% already paid by AA in Country X.
解説:
| 問題 #1 正解: 会員のみ閲覧可能 | 問題 #2 正解: 会員のみ閲覧可能 | 問題 #3 正解: B | 問題 #4 正解: B | 問題 #5 正解: C |


 品質保証JPshikenは試験内容に応じて作り上げられて、正確に試験の内容を捉え、最新の99%のカバー率の問題集を提供することができます。
 一年間の無料アップデートJPshikenは一年間で無料更新サービスを提供することができ、認定試験の合格に大変役に立つます。もし試験内容が変えば、早速お客様にお知らせします。そして、もし更新版がれば、お客様にお送りいたします。
 全額返金お客様に試験資料を提供してあげ、勉強時間は短くても、合格できることを保証いたします。不合格になる場合は、全額返金することを保証いたします。(
 ご購入の前の試用JPshikenは無料でサンプルを提供することができます。無料サンプルのご利用によってで、もっと自信を持って認定試験に合格することができます。

